HL Hunt's Metro 2 software combines automated validation with $99-a-month starter pricing
The product page markets field mapping, validation against more than 200 rules and dispute management, with plans priced by reported tradelines while separate terms describe high-volume record-based tiers.
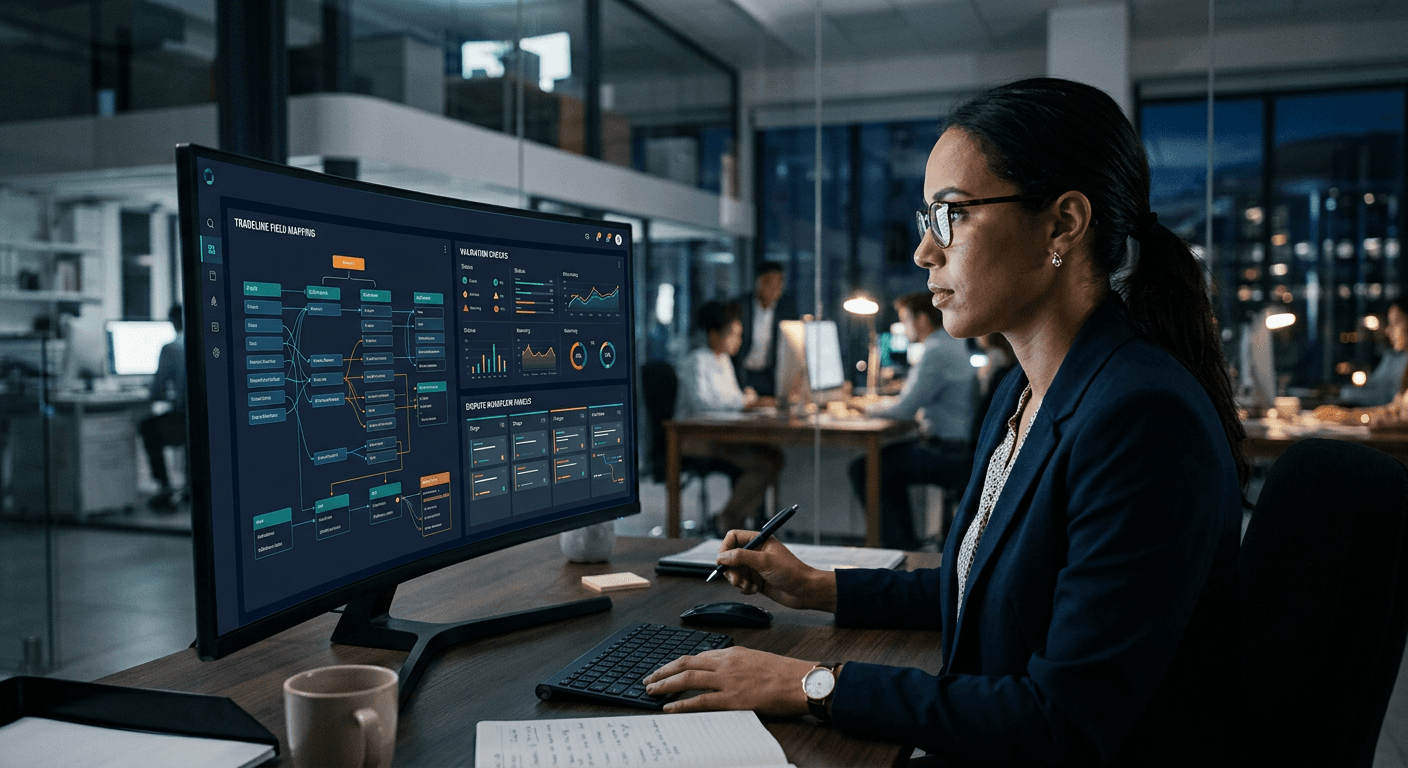
HL Hunt Financial markets its Metro 2 Reporting Software to lenders and furnishers that need to prepare and submit consumer-account data to credit bureaus. The product page describes automated field mapping, validation against more than 200 rules and dispute-management workflows.
The public marketing tiers are Starter at $99 per month for up to 500 tradelines, Business at $299 per month for up to 5,000 tradelines, and Enterprise with custom pricing for unlimited tradelines. The page says the pricing is volume-based and has no setup fees or contracts.
HL Hunt also publishes higher-volume professional terms that use a different unit: Essential is listed at $2,500 per month for up to 50,000 records, with an $0.08 overage fee, while Professional is $7,500 per month for up to 500,000 records, with an $0.03 overage fee. Those figures and record-based terms do not appear in the simple three-tier marketing table, so a prospective customer would need to confirm which schedule applies to its account.
The product's practical value depends on the quality of its mappings and validation rules, but the company does not publish an independently audited error rate, dispute-resolution result or bureau-acceptance rate on the product page. Validation software can help identify missing or inconsistent fields; it does not by itself transfer the furnisher's legal responsibility for accurate, complete and timely reporting.
HL Hunt's published materials describe the product's capabilities and prices but do not establish a guaranteed credit outcome for consumers or a compliance safe harbor for furnishers. Lenders considering the service would still need to review their reporting controls, data governance and dispute procedures.